It’s official: the standard Medicare Part B premium 2027 will be $209.40 a month, up $6.50 (3.2%) from $202.90 in 2026. CMS announced the new amount on November 17, 2026, along with a higher Part B deductible of $292. For most retirees, the increase comes straight out of their Social Security check in January, the same month the 3.6% COLA arrives. This guide shows how much of your raise you’ll actually keep, who pays more than $209.40, and how to lower or appeal your premium.
Medicare Part B Premium 2027: The New Numbers
| Medicare cost | 2026 | 2027 | Change |
|---|---|---|---|
| Standard Part B premium (monthly) | $202.90 | $209.40 | +$6.50 |
| Part B premium (yearly) | $2,434.80 | $2,512.80 | +$78 |
| Part B deductible | $283 | $292 | +$9 |
| Part A hospital deductible | $1,736 | $1,776 | +$40 |
| Part A coinsurance, days 61–90 | $434/day | $444/day | +$10 |
| Skilled nursing coinsurance, days 21–100 | $217/day | $222/day | +$5 |
CMS says the increase is mainly due to expected growth in health care spending. By law, the standard premium covers about 25% of Part B costs for people 65 and older, so when spending rises, premiums follow. You can see every figure in the official CMS 2027 fact sheet.
A married couple who both pay the standard premium will pay $5,025.60 for Part B in 2027, about $156 more than in 2026.
Medicare Part B Premium 2027 vs. Past Years
Here’s how the standard Medicare Part B premium 2027 compares with recent years:
| Year | Standard monthly premium | Change from prior year |
|---|---|---|
| 2023 | $164.90 | −$5.20 |
| 2024 | $174.70 | +$9.80 |
| 2025 | $185.00 | +$10.30 |
| 2026 | $202.90 | +$17.90 |
| 2027 | $209.40 | +$6.50 |
That’s a rise of about 27% in four years. The good news is that the 2027 increase is the smallest since 2023, and it’s smaller in percentage terms than this year’s COLA.
How Much of Your COLA Will You Keep?
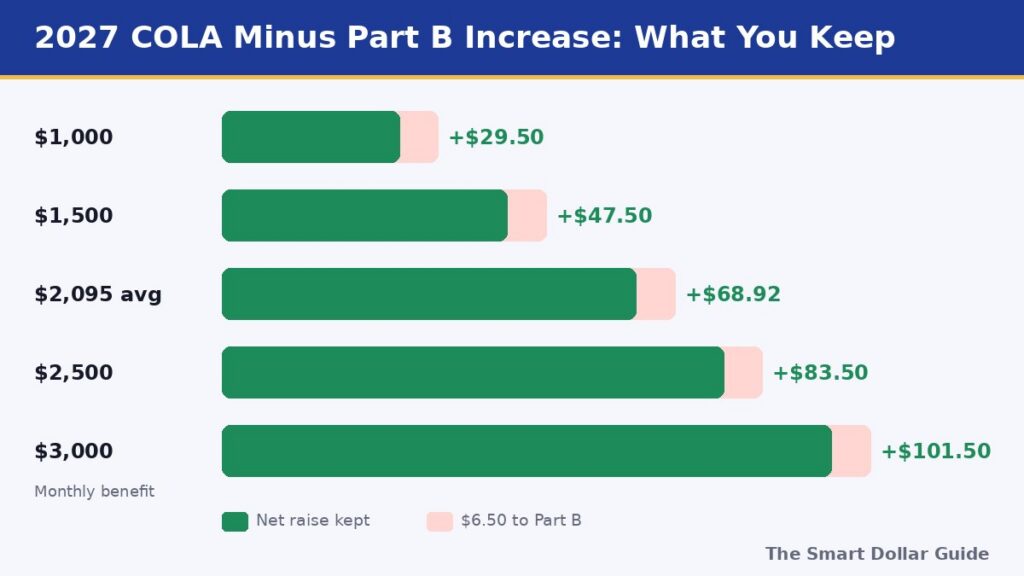
Social Security benefits rise 3.6% in January 2027. If your Medicare Part B premium 2027 amount is deducted from your check, your net raise is your COLA minus $6.50. Here’s what that looks like at different benefit levels:
| Monthly benefit (2026) | 3.6% COLA | Part B increase | Net raise you keep |
|---|---|---|---|
| $1,000 | +$36.00 | −$6.50 | +$29.50 |
| $1,500 | +$54.00 | −$6.50 | +$47.50 |
| $2,095 (average retiree) | +$75.42 | −$6.50 | +$68.92 |
| $2,500 | +$90.00 | −$6.50 | +$83.50 |
| $3,000 | +$108.00 | −$6.50 | +$101.50 |
These are estimates. SSA rounds benefits down to the nearest dollar, and Part D or Medicare Advantage premiums taken from your check can change too. In short, the average retiree keeps about $69 of a $75 raise, or roughly 91%. For more on the raise itself, see our Social Security COLA 2027 guide.
Can the premium make your check go down?
Almost never this year. A rule called “hold harmless” stops your Social Security check from shrinking because of a Part B premium increase. But it only kicks in when the COLA, in dollars, is smaller than the premium increase. With a 3.6% COLA, any benefit above about $181 a month gets a raise bigger than $6.50, so nearly everyone pays the full new Medicare Part B premium 2027 amount and still sees a slightly bigger check.
Hold harmless doesn’t protect people who are new to Medicare in 2027, people who don’t have the premium taken from Social Security, or anyone who pays IRMAA.
Who Pays More Than $209.40? The 2027 IRMAA Brackets
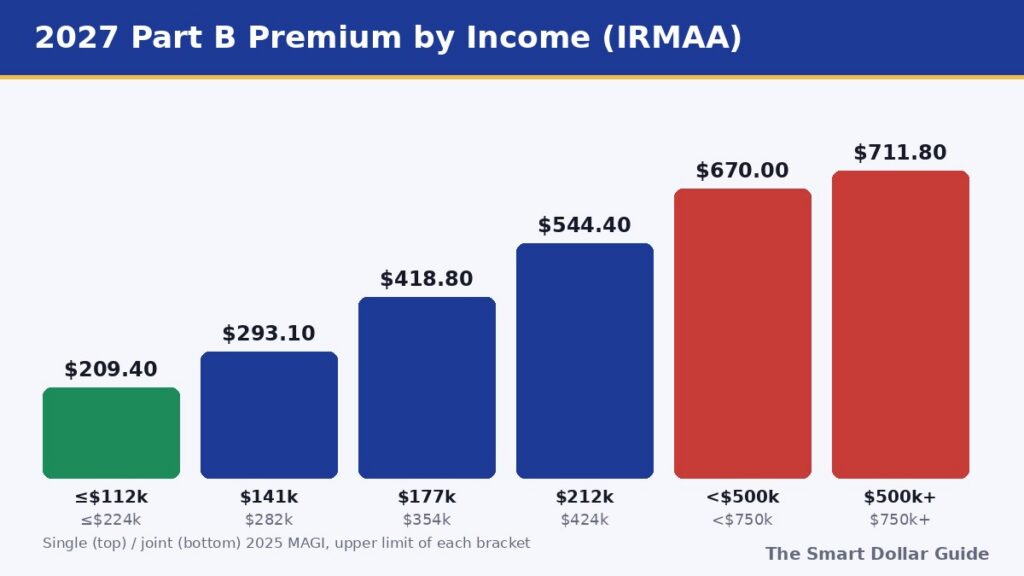
Not everyone pays $209.40. Higher earners pay an income-related monthly adjustment amount, or IRMAA, on top of the standard Medicare Part B premium 2027. It’s based on your modified adjusted gross income from your 2025 tax return, two years earlier.
| 2025 income (single) | 2025 income (joint) | 2027 Part B premium | Part D surcharge |
|---|---|---|---|
| $112,000 or less | $224,000 or less | $209.40 | $0 |
| $112,001–$141,000 | $224,001–$282,000 | $293.10 | +$15.40 |
| $141,001–$177,000 | $282,001–$354,000 | $418.80 | +$39.70 |
| $177,001–$212,000 | $354,001–$424,000 | $544.40 | +$64.00 |
| $212,001–$499,999 | $424,001–$749,999 | $670.00 | +$88.30 |
| $500,000 or more | $750,000 or more | $711.80 | +$96.40 |
The IRMAA brackets work like cliffs, not slopes. Going just $1 over $112,000 as a single filer raises your Part B premium by $83.70 a month, or about $1,004 a year, plus the Part D surcharge. For a married couple, that’s over $2,000 a year from a single extra dollar of income.
Planning tip for 2027 and beyond
Because IRMAA looks back two years, the income you report for 2026 sets your 2028 premiums. If you’re near a bracket edge, a Roth conversion, a large IRA withdrawal or a big capital gain this year could push you over. Our year-end tax moves checklist covers moves to make before December 31.
How to Appeal IRMAA After a Life-Changing Event
If your income has dropped since 2025, you don’t have to wait two years for your premium to fall. Ask Social Security to use a more recent year by filing Form SSA-44. Qualifying life-changing events include:
- You stopped working or cut back your hours (retirement counts)
- Marriage, divorce or annulment
- Death of a spouse
- Loss of income-producing property, such as from a disaster
- Loss or reduction of a pension
- An employer settlement payment
Include proof, such as a letter from your employer showing your retirement date, and an estimate of your current-year income. Many people who retired in 2025 or 2026 qualify and can save over $1,000 a year.
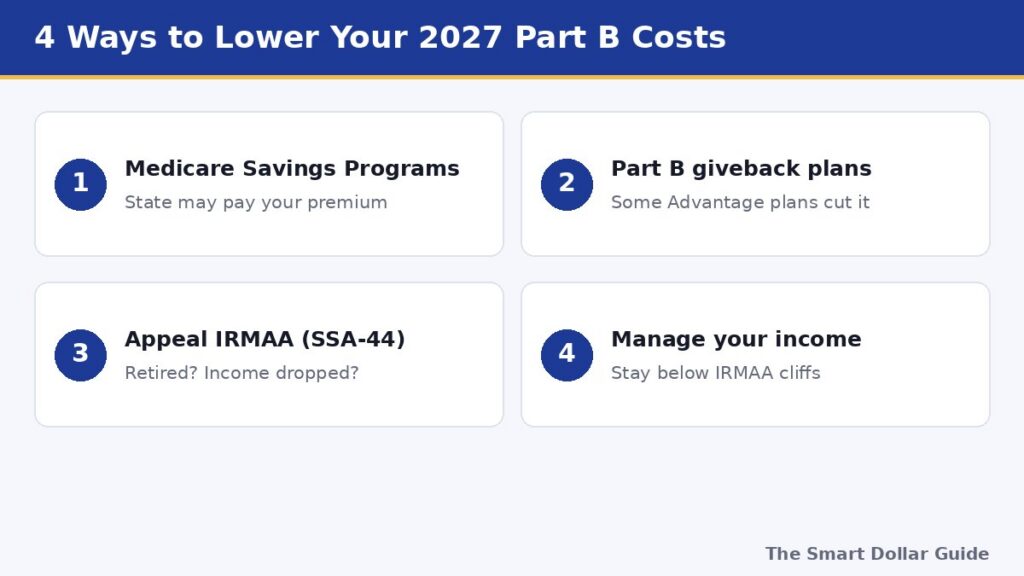
4 Ways to Lower Your Medicare Part B Premium 2027 Costs
- Check Medicare Savings Programs. If your income and savings are limited, your state may pay your Part B premium, and sometimes your deductible and copays too. Income limits vary by state, so apply even if you think you’re slightly over.
- Look for a Part B “giveback” plan. Some Medicare Advantage plans reduce your Part B premium by a set amount each month. Compare total costs, not just the giveback, using the Medicare Plan Finder before December 7.
- Check for the $90 Part B payment. Some plans and programs offer help with premiums; our post on the $90 Medicare Part B payment explains who actually qualifies.
- Manage your income. Stay below IRMAA cliffs when you can, use qualified charitable distributions from an IRA if you’re 70½ or older, and spread large withdrawals across years.
What to Expect in January 2027
Social Security mails COLA notices in December, and you can also see yours in your my Social Security account. Your notice will show your new gross benefit, your Medicare Part B premium 2027 amount ($209.40 for most people) (or your IRMAA amount) and your net payment. Check it carefully. If the premium looks wrong, for example, if you’re charged IRMAA after retiring, call Social Security right away. And if you pay the premium yourself rather than through Social Security, update any automatic payments to the new amount.
Final Thoughts
The Medicare Part B premium 2027 rises to $209.40 a month, a $6.50 increase that takes only a small bite out of the 3.6% COLA. The average retiree keeps about $69 of a $75 raise. Higher earners should check the IRMAA brackets and file Form SSA-44 if their income has dropped, and people with limited income should apply for a Medicare Savings Program. For more Medicare guides, visit our Medicare section.
Disclaimer: This article is for general information only and is not financial, tax or insurance advice. Premium and IRMAA figures are from CMS as of November 17, 2026. Net raise examples are estimates. Contact Medicare or Social Security about your own situation.
Frequently Asked Questions
What is the Medicare Part B premium for 2027?
The standard Part B premium is $209.40 a month in 2027, up $6.50 from $202.90 in 2026. CMS announced it on November 17, 2026.
What is the 2027 Part B deductible?
The annual Part B deductible rises to $292 in 2027, up $9 from $283 in 2026.
How much of my 2027 COLA will I keep?
Your net raise is your 3.6% COLA minus the $6.50 premium increase, if the premium is deducted from your check. The average retiree, with a $2,095 benefit, keeps about $69 of a $75 raise. This is an estimate.
Who pays more than $209.40 for Part B?
People with 2025 modified adjusted gross income above $112,000 (single) or $224,000 (married filing jointly) pay IRMAA surcharges, with total premiums from $293.10 to $711.80 a month.
Can I lower my IRMAA if I retired?
Yes. If your income dropped because of a life-changing event such as retirement, divorce or the death of a spouse, you can ask Social Security to use more recent income by filing Form SSA-44.
Can the Part B increase reduce my Social Security check?
For most people, no. The hold harmless rule prevents your net check from falling because of a premium increase, and a 3.6% COLA exceeds $6.50 for anyone with a benefit above about $181. It doesn’t protect new enrollees, IRMAA payers or people who pay the premium directly.
Sources
- CMS – 2027 Medicare Parts A & B Premiums and Deductibles (Nov 17, 2026)
- SSA – Form SSA-44, Medicare IRMAA Life-Changing Event
- FedSmith – What federal retirees will pay for Medicare Part B in 2027
- Senior Health Times – Medicare Part B premium rises to $209.40 a month for 2027
- Washington Times – Medicare Part B premium to rise 3.2% to $209.40 a month in 2027